
+- ShareholdersUnite Forums (http://shareholdersunite.com/mybb)
+-- Forum: Companies (http://shareholdersunite.com/mybb/forumdisplay.php?fid=1)
+--- Forum: New Stock Ideas (http://shareholdersunite.com/mybb/forumdisplay.php?fid=7)
+--- Thread: Ambarella (AMBA) (/showthread.php?tid=10050)
Ambarella (AMBA) - admin - 04-09-2016
By Chris Lange April 8, 2016 11:20 am EDT
The proliferation of smart devices and ubiquitous access to broadband connections are driving exponential growth in the capture, transmission, consumption and analytics of video content. One key analyst sees Ambarella Inc. (NASDAQ: AMBA) products as uniquely positioned to enable a new wave of professional and consumer devices to capture and stream high-quality video with real-time analytics. However this is a somewhat neutral view.
Oppenheimer initiated coverage of Ambarella with a Perform rating and no price target. The firm sees Ambarella as one of the best pure-play investments in a future of computer vision and intelligent image- capturing devices. However, it believes the risk-reward profile is balanced for now, considering the unfavorable outlook for major end markets in the near term, timing uncertainty for the market trends that support its future growth and what Oppenheimer sees as a fair valuation.
Ambarella provides the highest-performance video processing systems-on-chips with the lowest power consumption, according to its management. The company’s proprietary video processing architecture and deep domain expertise in video processing and delivery make the company the go-to high-end solution provider in markets such as IP camera, wearable camera, drone camera and automotive dashboard cameras.
The brokerage firm sees intelligent video processing becoming the must-have feature across multiple end markets, a trend from which it believes Ambarella is well positioned to benefit. However, Oppenheimer sees near-term interruptions from the action and IP camera markets, which are 70% of revenues. This prompts a reset of the long-term growth outlook with more conservative assumptions.In its report Oppenheimer detailed:
Ambarella may find significant future growth from a number of verticals such as drones, automotive OEMs, and the Internet of Things. But we believe the timing of these markets’ inflection points is more than a few quarters away as all participants are still exploring and developing clear business models and sustainable growth of revenues and profits.
Shares of Ambarella were trading at $44.73 on Friday, with a consensus analyst price target of $57.55 and a 52-week trading range of $33.39 to $129.19.
RE: Ambarella (AMBA) - admin - 04-09-2016
Written by Ophir Gottlieb on April 1st, 2016. First posted on: news.cmlviz.com
PREFACE
There’s a small cap tech marvel that is participating in some of the most radically innovate themes moving technology forward that has been crushed by the market. The stock has dropped from just below $130 in July, to $35 and has recently bounced back to $45 on big news.
But here’s the secret: Wall Street has overreacted and thrown the baby out with the bathwater.
STORY
We are now looking at a technology company with a $1.5 billion market cap at an all-time high in revenue, turning a healthy profit and now setting foot in thematic trends that show extraordinary growth.
AMBA’s most recent tumble came after GoPro (GPRO) reported another atrocious quarter. GPRO is AMBA’s largest customer, making up fully 30% of revenue. But friends, things have gotten totally out of control with Ambarella and the bearish herd has gone too far.
THE COMPANY
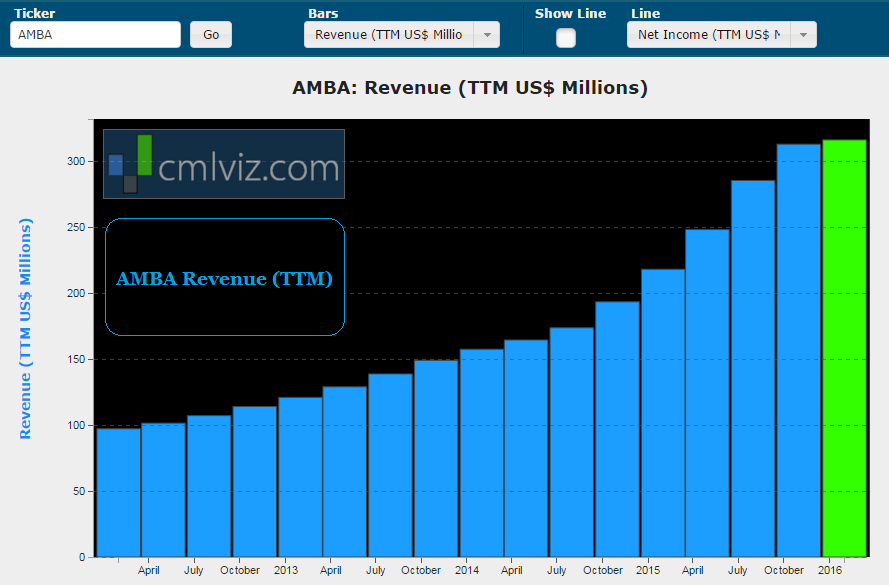
AMBA is a maker of high-definition video chipset and compression software which means it spans all of technology from AAPL and GOOGL to TSLA, INTC, QCOM and NVDA. The stock is down, but oh how the tide is turning. Let’s start with a chart of revenue (TTM) for all-time.
Discover the Undiscovered:
Get Our Free News Alerts Twice a Week.
Ambarella’s revenue is up 50% year-over-year to now over $300 million in the trailing-twelve-months. Now, that growth is coming to a bit of halt – call it a pause as GoPro goes through a disastrous demand problem with its products.
But the key here for AMBA is how it has placed itself in some of the most powerful and transformative technology trends in the world. Here we go:
TRANSFORMATIVE THEMES: DRONES
First, as a video chipset maker, we can think of AMBA as the “eyes” to technology. It’s certainly not the only one, but it has a product which has set itself apart. Let’s start with the drone market:
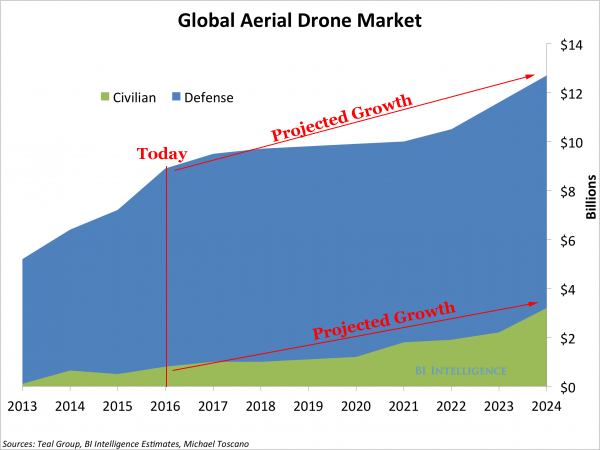
The drone was named as one of the four critical new technologies at the Consumer Electronics Show (CES) this year and we can see how the market has legs to grow. Morgan Stanley’s Joseph Moore just wrote a bullish note on Ambarella – we’ll take bits and pieces of it as it fits in the broader scope of the company’s technological innovation. Here’s what he had to say about drones:
2. Ambarella generated over 10% of last year’s revenues from drones, at margins well above the corporate average.
3. He believes that Ambarella will see several new drone product launches over the course of 2016.
Source: Barron’s
Moore goes on to warn of competition from Qualcomm (QCOM) and Intel (INTC) – certainly true, so much so that AMBA could be a takeover candidate if it makes too much headway in this market. But there’s so much more.
Amazon.com (AMZN) is soon to be using a fleet of drones that will make delivery times measured in minutes. It’s an astounding disruption in and of itself, but the demand for drones is going to explode as this type of customer connection becomes the standard.
AMBA is positioned beautifully for the growing drone segment.
TRANSFORMATIVE THEMES: SURVEILLANCE
Ambarella’s chip-sets (eyes of the camera) are making headway in to the less than sexy but explosive video surveillance market. Here’s that chart from Statista:
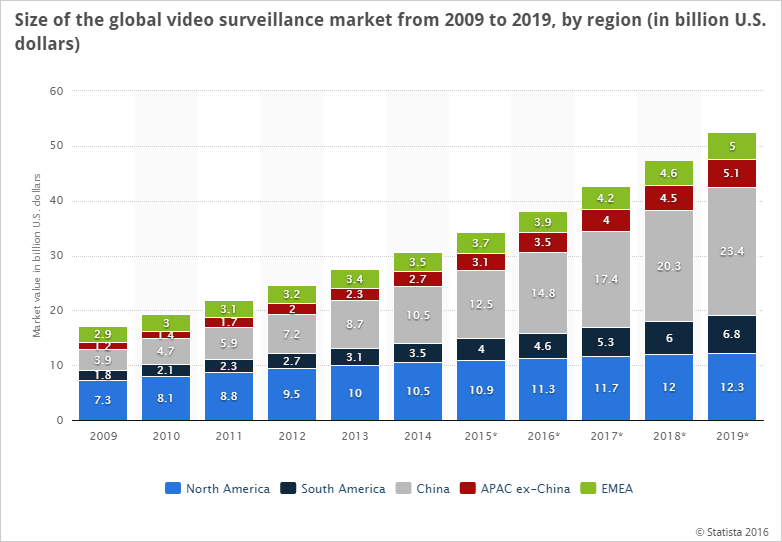
Gone are the days of the black and white, grainy convenience store surveillance cameras. We now live in a world where surveillance is not an afterthought – it’sthe thought. This goes to the commercial side as well as the enormous government surveillance programs.
TRANSFORMATIVE THEMES: SELF-DRIVING CARS
Ambarella will be producing a “computer vision chip.” This is how Moore describes it (emphasis added):
Initial use cases will be in drones and security cameras, though Ambarella expects to see its computer vision chip enabled for use in automotive OEMand Tier 1 within two years of taping out the chip.
Stop there. Now we’re talking about the self-driving featured market for automobiles. Here is the theme AMBA is after:
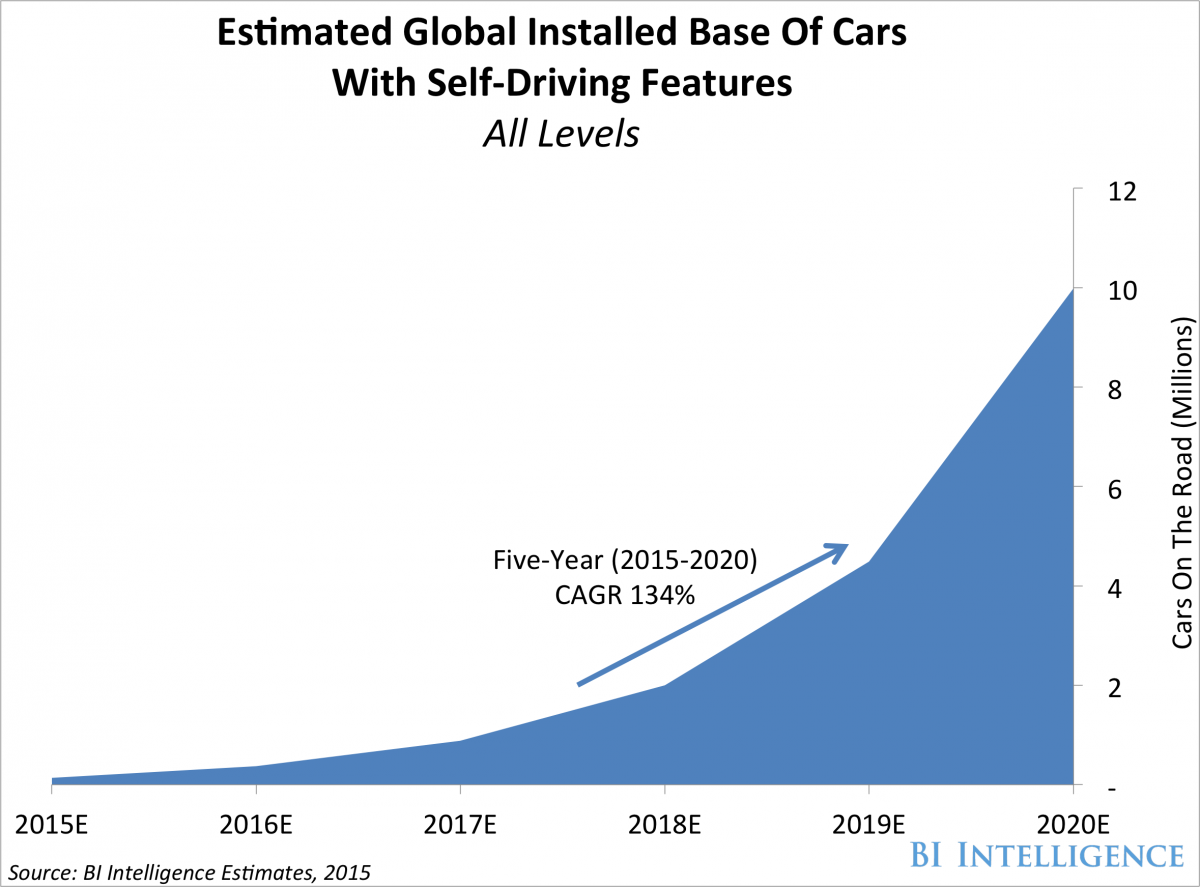
We’re looking at 134% compounded-annual-growth rate for the next five years ending at 10 million cars by 2020.
AMBA is entering the Advanced driver assistance systems (ADAS) market. Remeber, Tesla’s (TSLA) Elon Musk calls the Apple (AAPL) Car “an open secret.” Ambarella now has a customer base that could include companies like Tesla (TSLA), General Motors (GM), Toyota ™, Apple (AAPL), Google (GOOG), BMW, and many others.
AMBA will be competing with Mobileye (MBLY), which in fact calls many of the companies listed above as customers already, but whatever success it has, it’s entering with foundation of strong technology into a market desperate for “more and better.”
Remeber, video-chipsets are the eyes – and so much of the self-driving technology today is based on artifical intelligence and deep learning – all of that requires the the visual cortex as the starting point. Apple, Google and Tesla already know it.

If we just peruse the AMBA website we get product descriptions with phrases like: 360-Degree Surround View; E-mirrors; Latency-free, video that outperforms; Advanced Driver Assistance Systems; Drive Recording.
All the catch-phrases you want from a firm that is already the “eyes” to other technologies.
Source: Ambarella
WHY THIS MATTERS
Let’ just turn back to Moore’s commentary, he did a bang-up job:
Source: Barron’s
Yes. Exactly. Ambarella has thrust itself forward yet again into the transformative themes that will drive technology for the decades to come, and, in a more general sense, the company has thrust itself into the guts of semi-conductor makers.
So what now? Is the stock a buy?
SEEING THE FUTURE
Start with true innovation, the kind that turns companies from small caps into mega caps, the kind that sees stocks double, triple or even quadruple, that only occurs when two critical phenomena collide.
Then, to go beyond the known names to find the ‘next Apple’ or 'next Google’ we must get ahead of the curve. This is what CML Pro does. Our research sits side-by-side with Goldman Sachs, Morgan Stanley and the rest on professional terminals, but we are the anti-institution and break the information advantage the top .1% have.
We have named the precious few 'Top Picks’ for CML Pro. Each company identified as the single winner in an exploding thematic shift like artificial intelligence, the cloud, Internet of Things, drones, biotech and more. In fact, here are just two of the trends that will radically affect the future that we are ahead of:
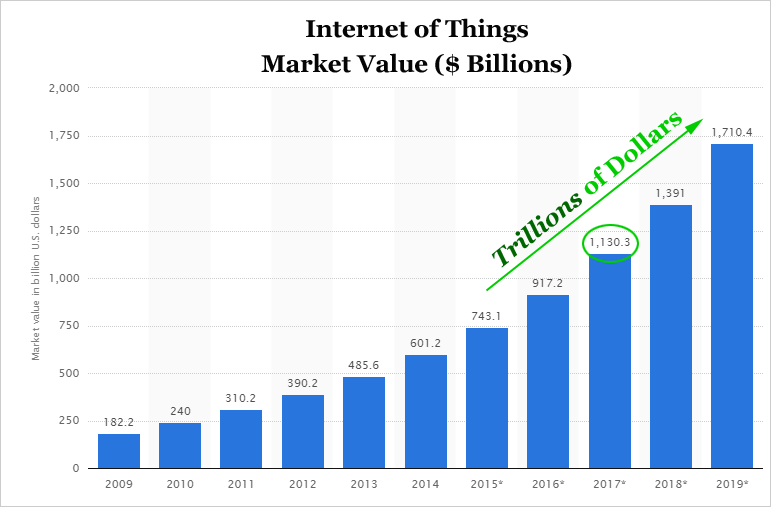
The Internet of Things (IoT) market will be measured in trillions of dollars as of next year. CML Pro has named the top two companies that will benefit.
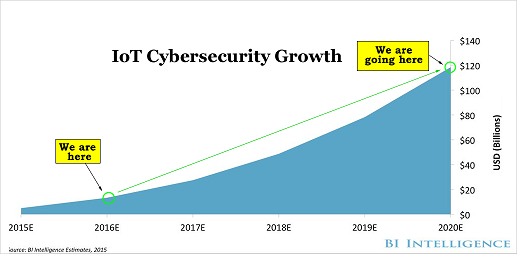
Market correction or not, recession or not, the growth in this area is a near certainty, even if projections come down, this is happening. CML Pro has namedthe single best cyber security stock to benefit from this theme.
These are just two of the themes we have identified and this is just one of the fantastic reports CML Pro members get along with all the visual tools, the precious few thematic top picks for 2016, research dossiers and alerts. For a limited time we are offering CML Pro at a 90% discount for $10/mo. with a lifetime guaranteed rate. Join Us: Get the most advanced premium research delivered to your inbox along with access to visual tools and data that until now has only been made available to the top 1%.
RE: Ambarella (AMBA) - admin - 05-13-2016
Ambarella falls as GoPro inventory glut drives Pacific Crest to cut outlook
Shares of GoPro (GPRO) chip supplier Ambarella (AMBA) dropped Thursday after Pacific Crest cut its price target on the shares to reflect slumping demand for the action camera brand, which the research firm argued has led to "massive," ongoing inventory corrections. RESETTING MODEL: Pacific Crest analyst Brad Erickson cut his price target on Ambarella to $53 from $62 this morning to reflect "massive" GoPro inventory corrections amid weaker demand for the action cameras. The analyst scrubbed his Ambarella model to account for the "full magnitude" of the past nine months of GoPro inventory adjustments, which Erickson noted appear to be continuing based on his April 24 checks. He estimates GoPro-derived revenue to fall 51% in Ambarella's 2017 due to excess channel fill last year. All that said, while there could be "slight" near-term risk to Ambarella's second quarter guidance -- with the timing of GoPro builds being the key determinant -- Erickson still sees the long-term risk/reward balance in Ambarella shares as favorable given that the name trades at just twelve times his 2018 estimates. Moreover, with 2017 revenue forecasts looking for a 1% dip, the analyst believes the market is "largely prepared" for a presumptive lowering of the company's annual target. "Much" negativity is already priced in, Erickson added, and his checks with drone retailers indicate sell-through rates in line with expectations. The analyst reiterates an Overweight rating on Ambarella. PRICE ACTION: Shares of Ambarella have declined 6.7% to $35.67 in afternoon trading, while GoPro has fallen 6.4% to $8.85.
Read more at:
http://thefly.com/landingPageNews.php?id=2374553
RE: Ambarella (AMBA) - admin - 05-25-2016
Xiaomi Corp., the Chinese smartphone maker that challenged Apple Inc. with sleek designs and low prices, is planning to introduce its first drone at a price more than 20 percent below a comparable product from market leader SZ DJI Technology Co., according to a person with direct knowledge of the matter. The drone, made by FIMI Technology, will record high-resolution 4K video and cost about 4,000 yuan ($610), the person said, asking not to be identified as the details are private. That compares with $799 for the Phantom 3 4K device on DJI’s website.
Xiaomi Pricing Its First Drone at $610 in Challenge to DJI - Bloomberg
Interesting to know what's inside..
Xiaomi is joining the crowd of upstarts in the drone market, hoping to take share from Shenzhen-based DJI, the leading seller of consumer devices. Today drones are still largely novelty items, with sales expected to reach almost 4 million this year and forecast to rise to 16 million by 2020. Newer players are targeting the lower-tiered part of the market, such as Syma Toys and Hubsan. Xiaomi is betting that it can capture a part of the consumer drone market that Grand View Research expects will reach reach $4.19 billion by 2024.
Xiaomi Pricing Its First Drone at $610 in Challenge to DJI - Bloomberg
RE: Ambarella (AMBA) - admin - 07-24-2016
Ambarella's shares have been down the last year because of problems at GoPro, one of their main customers. However, these are receding.
Wearable camera maker iON Worldwide was once GoPro's (NASDAQ:GPRO) largest rival. iON controlled 12% of the global action camera market in 2014, according to IDC, compared to GoPro's 48% share and Sony's (NYSE:SNE) approximate 8% share. However, iON recently filed for bankruptcy, stating that its revenue declined from $25 million to $12.4 million between 2014 and 2015, and that it was $15 million in debt.
GoPro's Biggest Rival Just Went Bankrupt -- The Motley Fool
RE: Ambarella (AMBA) - admin - 09-02-2016
We have to agree with that, the stock has rallied over 100% from the lows in March and April..
Ambarella is scheduled to report FQ2 earnings after the closed on September 1. The stock has rallied over 100% off the lows in part due to excitement over the release of two key products my previous top customer GoPro. Without the GoPro products shipping, the market is bound to face disappointment over the guidance for FQ3.
Ambarella: Market Expects Too Much From FQ3 Guidance - Ambarella (NASDAQ:AMBA) | Seeking Alpha
RE: Ambarella (AMBA) - admin - 09-03-2016
They nailed it pre-earnings (see previous entry)
Prior to the report, my research suggested the image processing semiconductor would struggle to meet lofty market expectations. After all, the stock surged 100% off the lows and the company was still expected to report FY17 results below the prior year levels. A lot of the excitement built on an expected rebound in the action camera market where key customer GoPro will launch a new product soon. My prediction though held that despite good numbers and high expectations, Ambarella was unwilling or unable to ratchet up guidance for the rest of the fiscal year. The management team has to take a conservative approach when business is relying on the sell-through of product by a customer with a recent history of underwhelming the market. As such, the CFO made the following statement on the earnings call: But I think with that said, you noticed we are having a reasonably strong Q3, but we have not changed our guidance for the year. And I think until we see sell-through in most of these consumer markets, we are to stay conservative.
Ambarella: Beating Conservative Guidance Isn't Enough - Ambarella (NASDAQ:AMBA) | Seeking Alpha
The stock is off 7%, despite a huge earnings beat.